
IT Department challenges tax deduction for compensation linked to Uphaar Cinema tragedy
New Delhi [India], October 15 (ANI): The Delhi High Court on Thursday issued notice to Ansal Theatre & Clubotels (P) Ltd. in an appeal moved by the Income Tax Department challenging the order of the Income Tax Appellate Tribunal (ITAT).
The matter arose with the expenditure claimed by Ansal in connection with the compensation given in the Uphar Cinema Fire tragedy case.
Division Bench of Justices Subramonium Prasad and Renu Bhatnagar issued notice on the appeal. The matter has been listed for hearing on February 5, 2027.
Senior Standing Counsel Vipul Agrawal appeared for the IT Department.
The Income Tax Department is challenging an order of the Income Tax Appellate Tribunal (ITAT) of November 22, 2023, in the case of Ansal Theatres & Clubotels (P) Ltd. for Assessment Year 2014–15.
It is stated that the dispute in the matter arises from expenditure claimed by the company in connection with compensation relating to the Uphaar Cinema fire tragedy and the legal proceedings arising from it.
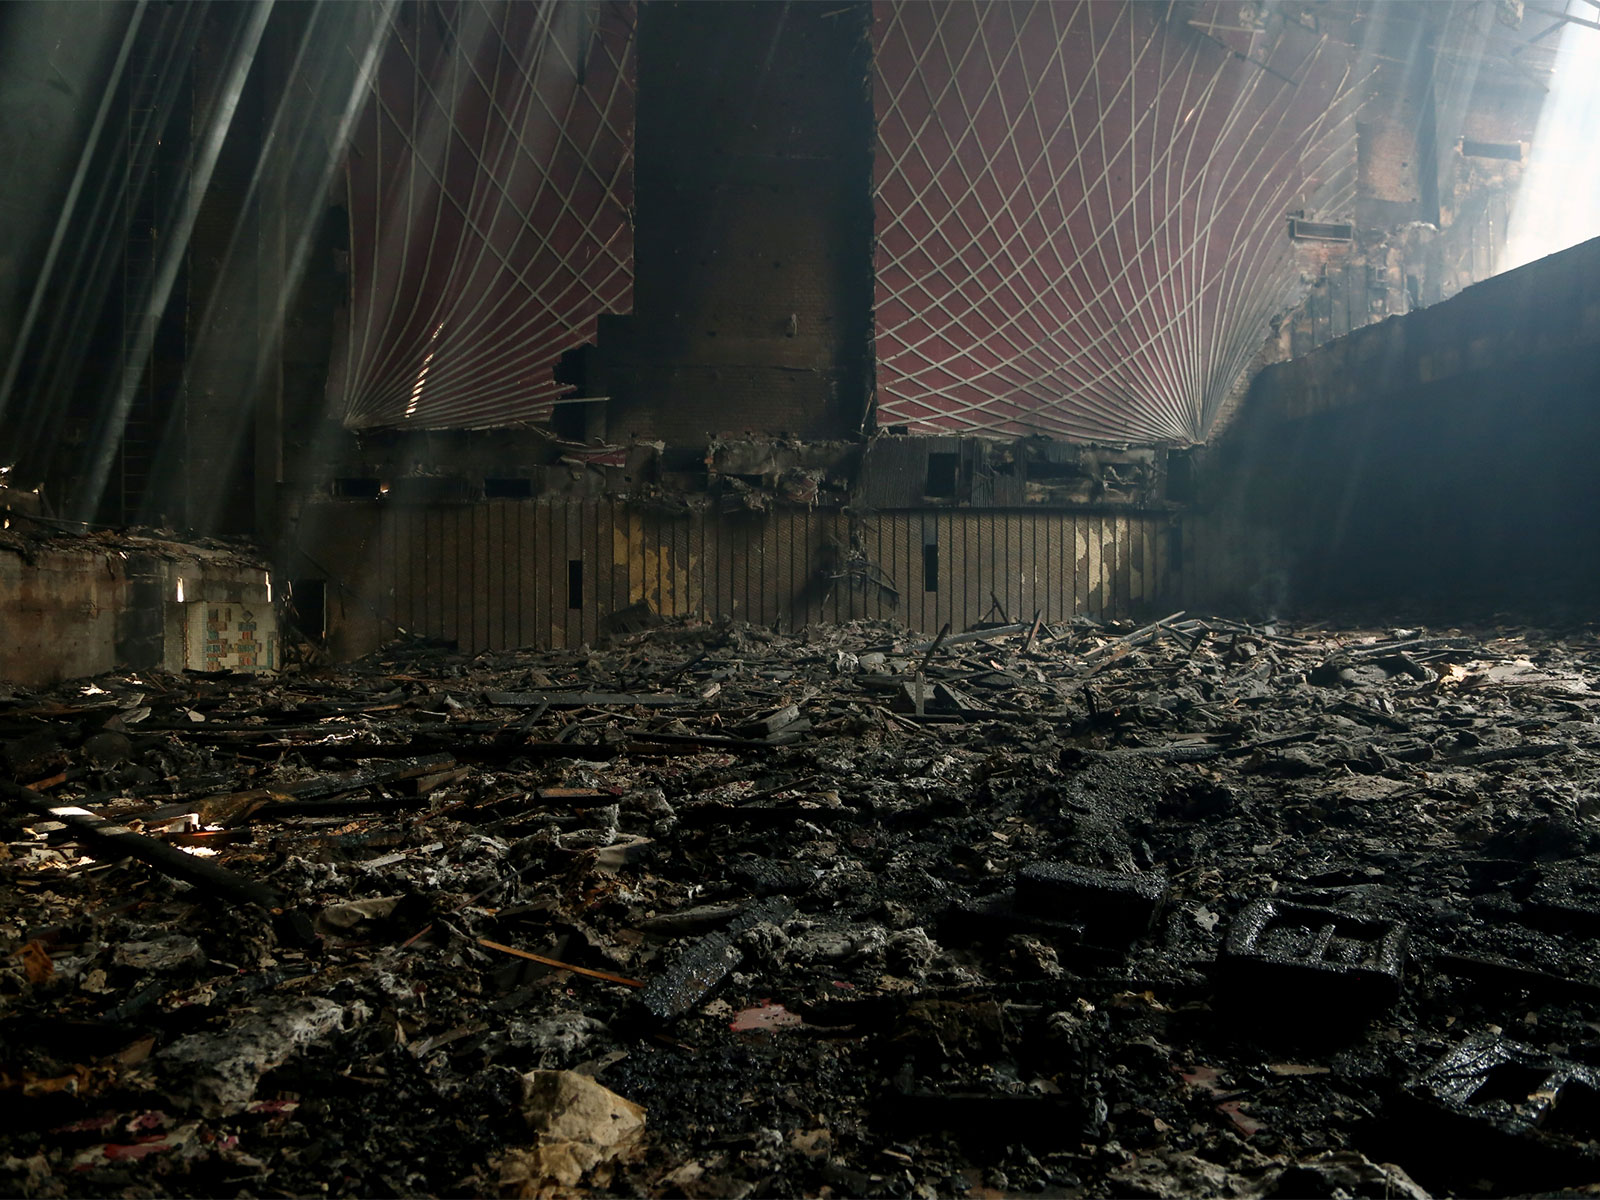
On 13 June 1997, a fire at Uphaar Cinema in Green Park, South Delhi, claimed the lives of 59 people and injured 103 others during a screening of the film Border. The tragedy led to prolonged legal proceedings concerning compensation to the victims and their families, as well as the liability of the cinema’s owners.
The IT Department said that for Assessment Year 2014–15, the assessee company claimed deductions totalling approximately ₹10.45 crore, comprising ₹8.81 crore towards compensation connected with the tragedy and ₹1.65 crore in legal and professional expenses.
The IT Dept. disallowed the entire claim, holding that the company had not sufficiently established that the expenditure was incurred wholly and exclusively for business purposes under Section 37(1) of the Income-tax Act, 1961. The Commissioner of Income Tax (Appeals) upheld the disallowance.
The ITAT, however, partly allowed the assessee company’s appeal, creating a distinction between compensatory and punitive damages.
It had directed that the disallowance be deleted except for ₹25 lakh representing punitive damages, and also allowed the legal and professional expenses claimed by the company
It is highlighted by the Department that a significant part of the dispute concerns the judgment of 13 October 2011 passed by the Supreme Court in a case titled Municipal Corporation of Delhi v. Association of Victims of Uphaar Tragedy, observing that this punitive damage is being allowed as negative restitution as “the Licensee is not only liable to pay compensation for the death and injuries, but should, in the least be denied the profits/benefits out of their illegal acts”.
The plea said that the ITAT created a distinction between restitution and negative restitution while deciding the assessee’s appeal. By its order of 22 November 2023, the Tribunal directed that the disallowance be deleted except for the ₹25 lakh in punitive damages and also allowed the legal and professional expenses claimed by the company.
The challenge therefore before the High Court concerns the tax deductibility of the expenditure—not the victims’ entitlement to compensation.
The Income Tax Department’s appeal seeks to contest this relief granted by the ITAT. The Department has questioned whether the compensation liability and the legal and professional expenses connected with the Uphaar-related litigation were sufficiently established to qualify as deductible business expenditure.
Its challenge also concerns whether the company demonstrated the necessary connection between the expenditure and its business, including whether the legal expenses were adequately substantiated and met the statutory requirements for deduction. (ANI)
